Business |
Minority Shareholder Oppression in Singapore: Your Rights and Legal Remedies
As a minority shareholder of a company, you may invariably find yourself being outvoted at shareholder meetings by majority shareholders.
However, mere disagreements between majority and minority shareholders are usually insufficient to demonstrate oppression. Oppression involves an element of unfairness, where majority shareholders use their dominant power to advance their interests at the expense of minority shareholders.
Fortunately, under Singapore’s law, there are rights and legal remedies available to minority shareholders in the case of oppression.
Who Counts as a Minority Shareholder in Singapore?
A minority shareholder is generally a member who lacks effective control of the company, and holding less than 50% of the voting shares is a common indicator rather than a legal requirement. Section 216 is available to a member of the company and does not impose a “less than 50%” threshold. The relevant question includes whether the claimant lacks effective control. Without effective control, they can be outvoted whenever a resolution comes up for a vote, a routine feature of company life that, on its own, is not unlawful.
The risk is sharper in private companies than in listed ones. A minority shareholder in a listed company can usually sell out on the open market if things sour. A public company is not necessarily listed, so its shareholders do not necessarily have an exchange-based exit. A minority shareholder in a private Singapore company often cannot, there’s no ready buyer, no listed price, and sometimes contractual restrictions on transferring shares at all.
That illiquidity is precisely what gives majority shareholders leverage to behave badly, and it’s why Singapore’s courts treat private-company minorities as needing real statutory protection.
What Legal Rights Do Shareholders Have?
The Companies Act 1967 gives every shareholder majority or minority a baseline set of rights.
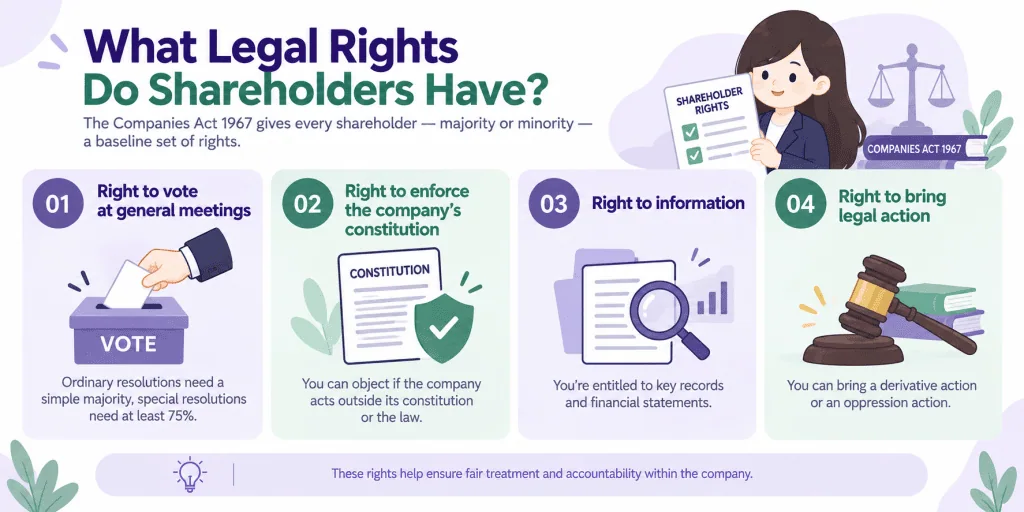
1. Right to vote at general meetings
Ordinary resolutions need a simple majority. Examples include appointing directors, approving the directors’ exercise of their power to issue shares (Section 161), and approving a disposal of the whole or substantially the whole of the company’s undertaking or property (Section 160). In these cases the resolution is the shareholders’ approval, while the directors implement the transaction itself. Not every disposal of company property requires a shareholder resolution. Special resolutions (changing the company’s name, converting from private to public, reducing share capital, approving a voluntary winding-up) need at least 75% of votes cast.
That 75% threshold matters more than it looks: a shareholder holding more than 25% of the voting shares may be able to block a special resolution at a general meeting, but only by exercising the relevant voting rights against it. Merely holding the shares without participating does not necessarily prevent the resolution from passing. Section 184 frames the meeting threshold by reference to the votes of members entitled to vote who vote in person or by proxy, so voting rights, the voting method and any applicable class restrictions also matter — a meaningful check even without control of the company.
2. Right to enforce the company’s constitution
If the company departs from its constitution or the Companies Act, any shareholder can object. A move into a different business is not, by itself, a breach of the constitution or the Companies Act, because Section 23 gives companies broad capacity, subject to applicable restrictions. It becomes a ground for objection where, for example, the constitution expressly restricts the company’s business, a reserved-matter provision requires shareholder consent to a change of business, or another relevant obligation is breached. Savvy minority shareholders negotiate additional protections up front, such as veto rights over new share issues that would dilute their stake.
3. Right to information
Shareholders are entitled to inspect certain company records, such as the electronic register of members, minutes of general meetings and the register of charges. The inspection rights and applicable procedures differ for each record, and these records do not all have to be supplied before a meeting.
Separately, a company must circulate its financial statements and accompanying documents before the relevant meeting, generally at least 14 days before it (or within five months of financial year-end for private companies that don’t hold one). This is a circulation requirement for financial statements and accompanying documents, not a general deadline for providing registers and minutes. Financial statements need not be audited where an audit exemption applies.
4. Right to bring legal action
A shareholder can apply to court for permission to sue on the company’s behalf (a derivative action), or sue in their own name if the company’s affairs are run in a manner oppressive or unfairly prejudicial to them, the basis of an oppression action.
Also Read: Shareholder Disputes in Singapore: Causes & How to Resolve Them
What Counts as Oppression Under Singapore Law?
Not every disagreement between shareholders amounts to oppression. The central consideration is commercial unfairness.
The courts assess the overall circumstances and whether the conduct complained of represents an unfair departure from the standards of fair dealing that shareholders could reasonably expect. Oppression may result from a single serious act or from a continuing pattern of conduct.
Examples of conduct that may support a Section 216 claim include:
- Dilution of minority shareholdings through improperly motivated share issues
- Denial of access to company information that the shareholder is legally entitled to receive
- Exclusion from management or decision-making where there was a legitimate expectation of participation
- Misuse of company funds or assets for the benefit of particular shareholders
- Sustained mismanagement that favours the personal interests of majority shareholders
- Withholding dividends without proper justification
However, the specific facts and circumstances remain important. Losing a shareholder vote, disagreeing with the company’s commercial strategy, or losing confidence in the board will not necessarily amount to oppression by itself.
Oppression in Quasi-Partnership Companies
Many Singapore private companies operate as quasi-partnerships. These businesses are often established and managed based on personal relationships, mutual trust and informal understandings between a small group of shareholders.
Because these arrangements may not always be governed by detailed shareholders’ agreements, disputes can arise when one party acts contrary to the expectations on which the business relationship was originally based.
The courts may take legitimate expectations into account when assessing whether conduct is commercially unfair. For example, shareholders may have operated on an informal understanding that each founder or family member would have a role in management or a seat on the board.
In appropriate circumstances, departing from such legitimate expectations may contribute to an oppression claim even where there has not been a straightforward breach of a written agreement.
Oppression Action vs Derivative Action
This is one of the most commonly confused points in shareholder disputes. The appropriate legal mechanism depends on whether the wrongdoing is primarily a personal wrong against the shareholder or a wrong against the company.
| Key Point | Oppression Action (s216) | Derivative Action (s216A) |
|---|---|---|
| Who sues | The minority shareholder, in their own name | The shareholder, on behalf of the company |
| What it addresses | Personal wrongs against the shareholder | Wrongs against the company itself |
| Typical trigger | Exclusion, dilution, denial of information, unfair prejudice | Director’s breach of fiduciary duty, misappropriation of company assets |
| Who benefits from the outcome | The minority shareholder personally | The company (and indirectly, all its shareholders) |
| Court permission needed first? | No | Yes — leave of court is required before filing |
In practice, the distinction can become complicated. Conduct involving misuse of company funds, for example, may cause harm to the company while also having a direct and unfair impact on a minority shareholder.
Determining whether the matter should proceed as an oppression action, derivative action, or potentially both therefore requires careful consideration of the nature of the wrongdoing and the remedy being sought.
How Are Minority Shareholder Disputes Resolved in Singapore?
Not every shareholder dispute needs to end up before a judge. In practice, disputes may move through several stages:
- Negotiation between shareholders: often the fastest and cheapest route, particularly where the relationship is worth preserving, as is common in family-run or quasi-partnership companies.
- Mediation: a neutral third party helps the shareholders reach a commercial resolution, such as a share buy-out on agreed terms, without the cost and publicity associated with litigation.
- Arbitration: if the shareholders’ agreement contains a valid arbitration clause, the dispute may need to be resolved through arbitration rather than court proceedings. Minority oppression claims are generally capable of being arbitrated in Singapore.
- Litigation under Section 216: where negotiation and mediation fail, or are not suitable, a shareholder may apply to the appropriate Singapore court for relief.
The appropriate starting point depends heavily on the shareholders’ agreement, the company’s constitution, the nature of the dispute, and whether preserving the business relationship remains realistic.
Also Read: The Complete Legal Audit Checklist for Singapore Companies (2026)
Legal Remedies for Minority Shareholder Oppression
Under Section 216(2) of the Companies Act, the court has broad discretion to order whatever relief it considers just and equitable in the circumstances. The available remedies are not necessarily limited to the specific relief initially requested by the claimant.
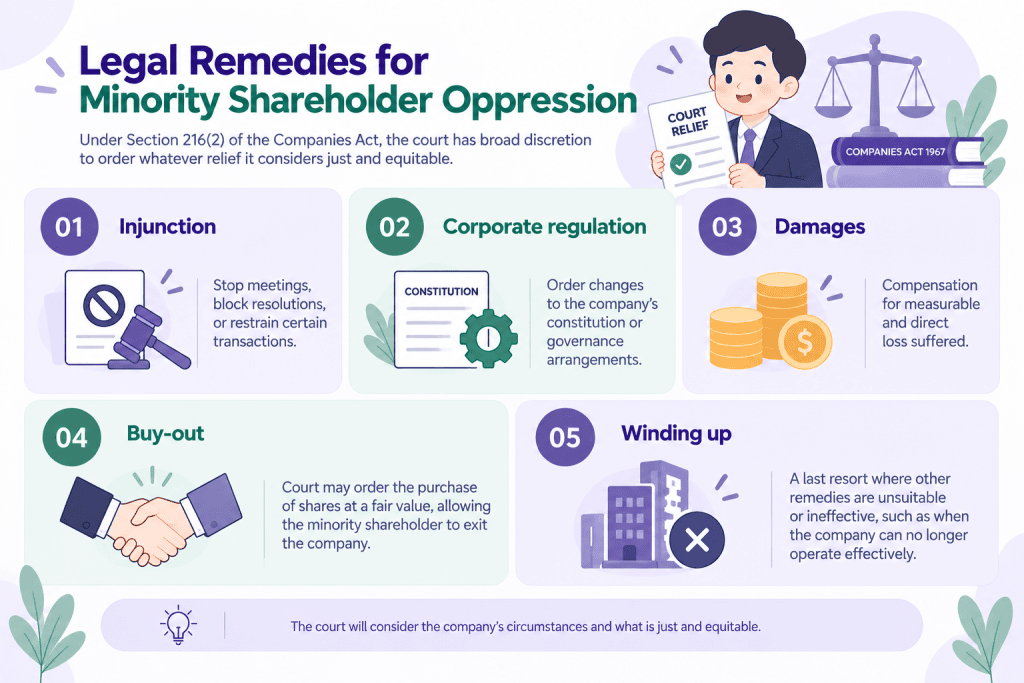
Injunction
The court can stop a general meeting from proceeding, prevent a board resolution from being implemented, or restrain the company from entering into a particular transaction.
Corporate regulation
The court can order changes to the company’s constitution or governance arrangements. Depending on the circumstances, this may include requirements concerning board appointments, voting procedures, or the operation of company bank accounts.
Damages
Damages may be available where the minority shareholder can establish a measurable and direct loss resulting from the conduct complained of.
Buy-out
Where the company remains viable, the court may order one shareholder or group of shareholders to purchase another shareholder’s shares at a fair value. This can provide the minority shareholder with an exit from the company.
The valuation process can itself become complex. When determining the appropriate price, the court may consider factors such as the company’s financial position, the nature of the shareholding, and whether any discount should be applied. A minority discount is not automatically appropriate in every case, and the valuation approach depends on the circumstances.
Winding up
Winding up is generally considered a last resort where other remedies are unsuitable or ineffective. It remains a remedy in the context of an established oppression claim, and a breakdown in the relationship between shareholders is not necessarily oppression on its own. It may become relevant where oppression has been established and, for example, the shareholders are irreconcilably divided or the company can no longer operate effectively.
How Can Companies Reduce the Risk of Oppression Claims?
The most effective safeguard is a properly drafted shareholders’ agreement, executed before disputes arise rather than after. It should clearly address decision-making rights, dividend policy, exit mechanisms, transfer restrictions, and what happens in the event of a deadlock.
Family businesses in particular may rely heavily on trust and informal arrangements instead of written documentation. While this can work when relationships remain positive, it can create uncertainty when disagreements arise.
Maintaining proper corporate formalities is therefore important. Companies should keep accurate board minutes, provide required financial information on time, properly document resolutions, and follow the company’s constitution and applicable statutory requirements.
Clear documentation helps protect both majority and minority shareholders and can reduce the risk of disagreements developing into formal oppression claims.
Been shut out, diluted, or unfairly outvoted as a minority shareholder?
RBN Chambers advises minority and majority shareholders on oppression claims, derivative actions, shareholder buy-outs, and dispute resolution from early negotiation through to litigation in the Singapore courts.
If you’re weighing up your options, an early conversation can help you understand where you stand before positions harden. Contact us here!
Frequently Asked Questions
What is the “25% rule” for minority shareholders in Singapore?
It refers to the blocking power that can come with holding more than 25% of a company’s voting shares. Because special resolutions generally require at least 75% approval, a shareholder or aligned group holding more than 25% may be able to block certain special resolutions without having majority control of the company. This requires the shareholder to exercise the relevant voting rights against the resolution at the general meeting, because merely holding the shares without participating does not necessarily prevent it from passing. Voting rights, the voting method and any applicable class restrictions also matter, and Section 184 frames the meeting threshold by reference to the votes of members entitled to vote who vote in person or by proxy.
Can a minority shareholder stop a company from being wound up?
A minority shareholder holding more than 25% of voting shares may be able to block a voluntary winding-up resolution by exercising the relevant voting rights against it, because it requires the approval threshold applicable to a special resolution. Merely holding the shares without participating does not necessarily prevent the resolution from passing, and voting rights, the voting method and any applicable class restrictions also matter. Where the majority is also engaging in conduct that may amount to oppression, an application under Section 216 may provide additional avenues for seeking appropriate relief.
How much does it cost to file a minority oppression claim in Singapore?
Costs vary widely depending on the complexity of the dispute, the amount of documentary and financial evidence involved, and how far the matter proceeds. A dispute resolved through early negotiation or mediation may cost considerably less than one that proceeds through a full trial or appeal.
Are minority oppression claims arbitrable in Singapore?
Generally, yes. Singapore courts have recognised that minority oppression claims can be arbitrated where there is a valid and applicable arbitration agreement. The precise position depends on the wording and scope of the arbitration clause and the nature of the dispute.
Delivering Solutions not just Answers to your legal disputes
We provide solutions to all our clients regardless of the scale or complexity of the cases. Let us know how we can help.
Contact UsAny information of a legal nature in this blog is given in good faith and has been derived from resources believed to be reliable and accurate. The author of the information contained herein this blog does not give any warranty or accept any responsibility arising in any way, including by reason of negligence for any errors or omissions herein. Readers should seek independent legal advice.